
Veterans & Military Homebuyers
You served. Let me help you come home.
Veterans, active-duty service members, Guard and Reserve members and surviving spouses: I'll help you put your VA home loan benefit to work, from your first search to the closing table.
Why Veterans work with me
A VA specialist who shows up for you.
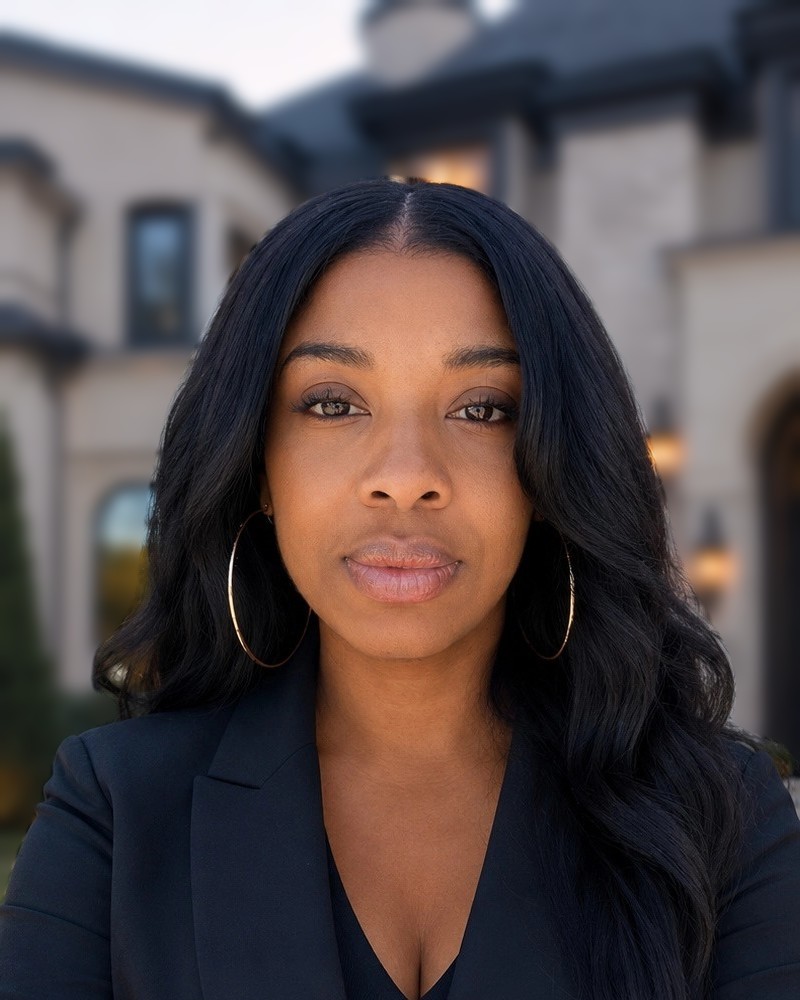
Serving Veterans and military families is a genuine passion of mine. Since 2008 I've learned how VA financing, entitlement and the appraisal process shape a purchase, what sellers and appraisers look for, and how to keep your timeline on track, whether you're buying your first home or using your benefit again.
Thank you for your service. It's an honor to help you come home.
Recognition
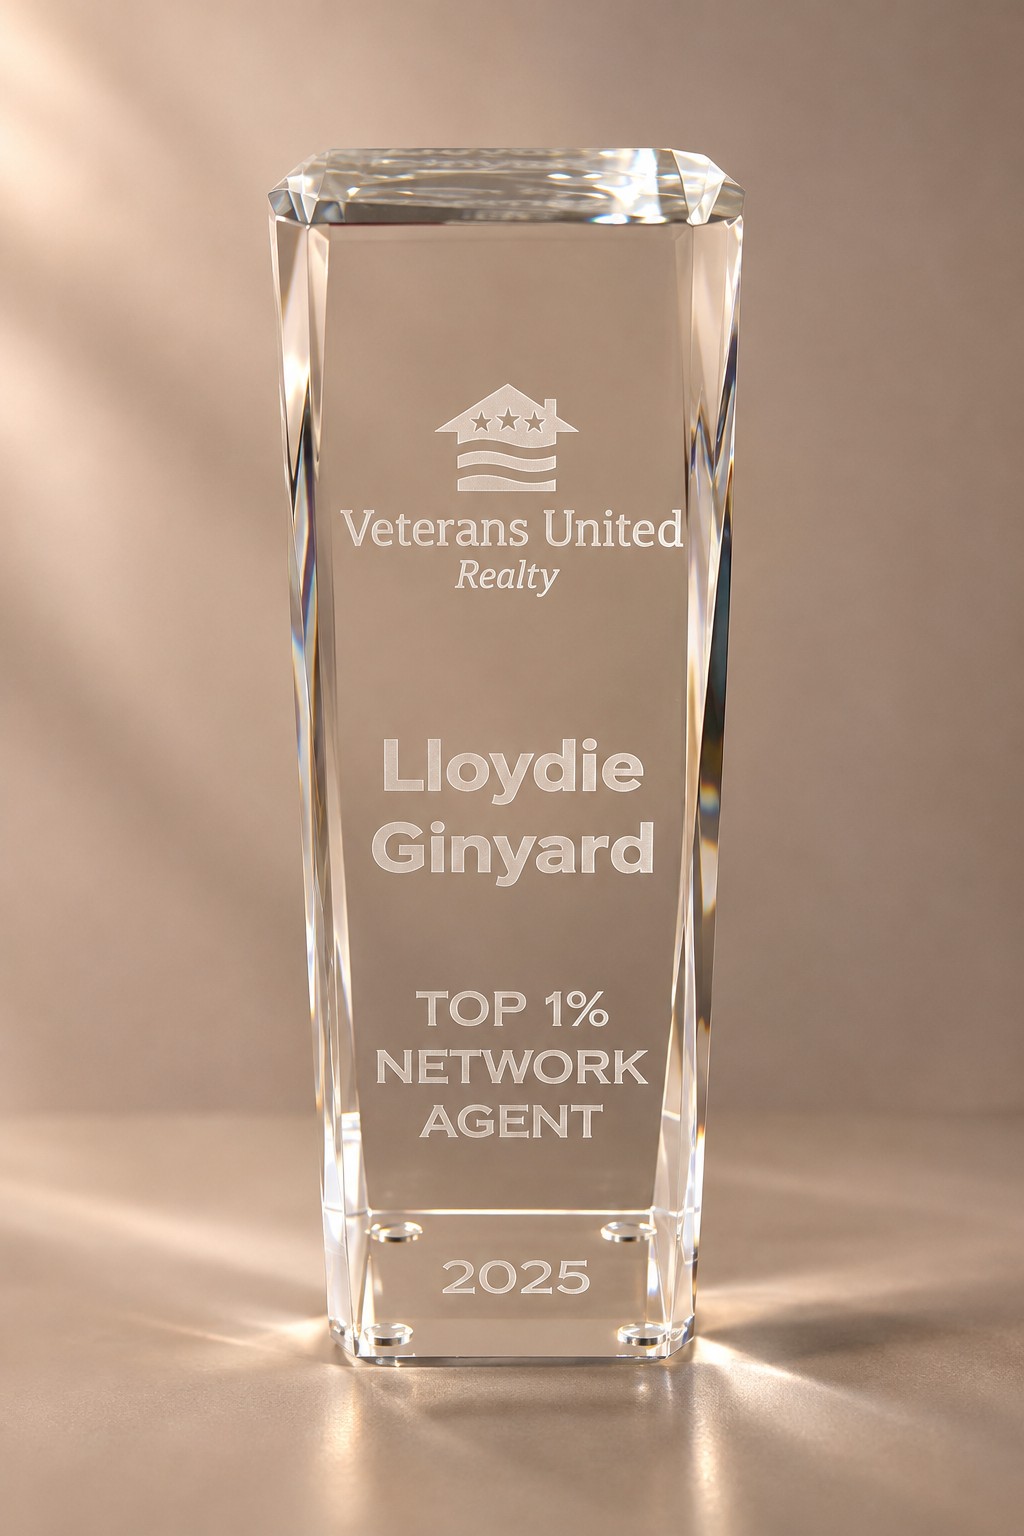
Top 1% Network Agent, Veterans United Realty, 2025.
This recognition represents more than professional achievement. It reflects my longstanding commitment to serving Veterans, active-duty service members, and military families. I consider it both a privilege and a responsibility to help those who have served our country understand and fully utilize the homeownership benefits they have earned.
Your VA benefit at a glance
What every VA buyer should know.
Benefits and eligibility
VA guarantees part of the loan, which lets lenders offer strong terms. VA-backed purchase loans generally don't require a down payment or monthly mortgage insurance. Veterans, service members, many Guard and Reserve members, and some surviving spouses may be eligible based on their service. VA decides eligibility, and your lender approves the loan.
Certificate of Eligibility
Your COE shows lenders you qualify. You can request it online at VA.gov, through your lender, or by mail with VA Form 26-1880. Veterans usually need their DD214. VA decides eligibility.
Entitlement and restoration
Entitlement is the amount VA will guarantee. With full entitlement, VA sets no loan limit, though your lender still decides how much you can borrow. If part of your entitlement is tied up in another VA loan, your remaining entitlement depends on the county loan limit. Entitlement can generally be restored after a VA loan is paid off, and your Certificate of Eligibility shows what you've used.
Buying with VA financing
A VA purchase works much like any other, with a few key differences: the VA appraisal, minimum property requirements, and rules about which closing costs you can pay. A well-written offer explains these clearly, so sellers see a strong, dependable buyer.
Funding fee and exemptions
Most buyers pay a one-time VA funding fee. You may be exempt if you receive VA compensation for a service-connected disability, are a surviving spouse receiving DIC, have a proposed or memorandum rating before closing, or are an active-duty Purple Heart recipient. Your lender and VA confirm this.
Appraisal and property requirements
Your lender orders a VA appraisal to estimate market value and confirm the home meets VA's minimum property requirements for a safe, sound and sanitary home. An appraisal isn't a home inspection, so I always recommend one too.
VA loan assumptions
Some homes come with an assumable VA loan, which may let a qualified buyer take over the seller's existing loan. Assumptions need lender approval. If the buyer isn't a Veteran substituting their own entitlement, the seller's entitlement can stay tied to that loan, so both sides should understand the trade-off.
Refinancing: IRRRL and cash-out
An Interest Rate Reduction Refinance Loan (IRRRL) is a streamlined refinance that replaces your current VA-backed loan with new terms, such as a lower rate or a move from adjustable to fixed. You must already have a VA-backed loan on the home and certify that you live or used to live there. A VA cash-out refinance is a separate option. Compare several lenders.
Surviving spouses
Some surviving spouses qualify, for example when the Veteran died in service or from a service-connected disability, or is missing in action or a prisoner of war. Remarriage rules apply. VA reviews each request.
Who I serve
Every chapter of military life.
First-time military homebuyers
A patient, step-by-step walk-through of your first purchase with a VA loan.
Active-duty service members
Timelines built around orders, report dates and virtual tours when you can't be here.
Veterans
Buying again, upsizing, downsizing or putting restored entitlement to work.
Families in transition
Military families leaving service or base housing and moving into a home of their own, plus eligible surviving spouses.
Why representation matters
A VA purchase deserves a knowledgeable advocate.
VA buyers can be every bit as strong as conventional buyers, but only when the offer, the timeline and the details are handled with care.
- —Offers sellers trust. Clear terms that answer listing agents' questions about VA financing before they're asked.
- —Homes that fit VA standards. Spotting likely minimum property requirement issues early, before they delay closing.
- —Appraisal and repair negotiation. Steady guidance if the appraisal comes in low or calls for repairs.
- —A team that knows VA. Introductions to experienced VA lenders, inspectors and closing attorneys.
How we'll do it
Five steps to the keys.
- 01Get your COE and pre-approvalI'll connect you with experienced VA lenders if you need one.
- 02Plan your searchBudget, commute, schools and your PCS or move-in timeline.
- 03Write a strong VA offerTerms that show sellers your offer is solid and ready to close.
- 04Inspection and appraisalI'll coordinate both and negotiate repairs when needed.
- 05Close and get your keysFinal walk-through, signing day and welcome home.
From military homebuyers
In their words.
“Very professional and knowledgeable, God sent!”
“She was excellent in every area of working for me, with me and getting me results.”
“My real estate agent was very active in making sure I found something on a timeline that worked for me.”
“I appreciated her clear communication and the way she kept me updated throughout the entire process… I felt that Lloydie genuinely had my best interests at heart.”
An important note
I'm a licensed real estate broker, not a lender or a representative of the Department of Veterans Affairs. VA determines eligibility and entitlement, and your lender determines loan approval, rates, fees and funding fee exemptions. The information here is general real estate guidance, not legal, tax or financial advice.
Let's connect
Thank you for your service. Let's find your home.
Send me a message
Tell me a little about your plans and I'll reach out personally. Prefer to talk now? Call or text 678-615-1485.
Contact Lloydie